This bibliometric study analyzed hospital audit research in China from 2010 to 2025 to identify publication trends, research hotspots, and emerging topics in risk management, digitalization, big data, and cybersecurity.
Research Article
Bibliometric Analysis of Hospital Audit Research in China (2010–2025): Trends and Emerging Research Topics
In This Article
Summary
Abstract
Hospital audits play an important role in improving organizational governance, financial accountability, and healthcare quality; however, the development of hospital audit research in China has not been comprehensively evaluated. The aim of this study was to identify research hotspots and emerging trends in hospital audit research in China using bibliometric analysis. Publications were retrieved from the China National Knowledge Infrastructure (CNKI) database using the subject terms “Hospital” and “Audit.” Chinese journal articles published between 2010 and 2025 were analyzed using VOSviewer 1.6.17 and CiteSpace 6.2R6 to evaluate publication trends, keyword co-occurrence, clustering, and burst detection. A total of 6,280 publications met the inclusion criteria. Keyword analysis identified internal audit, financial management, cybersecurity, medical equipment, risk management, and recommendations as the major research hotspots. Keyword clustering demonstrated distinct thematic groups with high clustering quality, whereas burst analysis indicated increasing research attention to big data, risk prevention and control, operational management, contract management, financial and accounting supervision, and audit rectification as emerging topics. These findings indicate that hospital audit research in China has expanded from traditional financial auditing toward broader operational, digital, and risk-oriented themes. The results provide a comprehensive overview of research development and may help inform future bibliometric investigations, hospital management practices, and evidence-based policy development.
Introduction
Hospital audit is not limited to financial or compliance reviews but encompasses a wide range of dimensions, including clinical service quality, patient safety, and resource utilization efficiency1. The core objectives of hospital audits include enhancing healthcare quality, ensuring patient safety, optimizing resource allocation, and strengthening organizational governance2,3. Studies have shown that effective audits not only identify issues but also drive behavioral change, especially when healthcare teams are aware that performance is being monitored4. As a crucial tool for improving healthcare quality, hospital audits have been widely implemented worldwide. From clinical services to financial management, and from individual departments to hospital-wide governance, the role of hospital audits has continually expanded. In China, the growing complexity of healthcare systems has intensified the need for rigorous auditing practices to improve operational efficiency, financial transparency, and overall patient care quality5. Given the Chinese government’s increasing efforts to enhance accountability in healthcare6, it is essential to analyze trends in hospital audit research within this context.
Bibliometric analysis provides an effective method for mapping the evolution of academic research in a specific field. Researchers can quantitatively assess the development trajectory of academic discourse, not only by identifying research hotspots but also by uncovering emerging trends and shifts in research priorities7.
This study proposes the use of bibliometric analysis to review hospital audit research in China from 2010 to 2025, leveraging its ability to process large volumes of literature to highlight publication trends, research hotspots, and emerging research frontiers. Traditional bibliometric analyses primarily focus on metrics such as publication counts, citations, and publication languages, often neglecting the thematic content of the research itself8. This study addresses this gap by combining general bibliometric findings with specific explanations of the major research topics identified. This approach aims to provide readers with a clearer understanding of the progress and emerging directions of hospital audit research. Additionally, it offers valuable insights for researchers interested in this field by facilitating the identification of major research trends and areas of continuing interest.
Protocol
Ethics approval was not required for this bibliometric study because it analyzed only publicly available published literature.
Data collection and processing
This study conducted a bibliometric analysis of the research hotspots and trends in hospital auditing in China. All data were retrieved from the China National Knowledge Infrastructure (CNKI) database because it is regarded as the premier academic database in China, in which published papers undergo a rigorous peer-review process. Retrieval of the bibliographic information used in this study did not require an institutional subscription or special access authorization. Therefore, no access restrictions affecting reproducibility were involved.
The subject terms “医院” (Hospital) and “审计” (Audit) were used to search the database for publications containing these terms in the Title, Abstract, or Keywords fields. To avoid changes in the retrieved records caused by frequent database updates, the search period was set from January 1, 2010, to December 31, 2025. The Subject field (which includes the Title, Abstract, and Keywords) was used to ensure comprehensive retrieval. The search query was constructed as follows: (Subject = “医院”) AND (Subject = “审计”). No restrictions were placed on subject categories during the initial search to avoid excluding potentially relevant interdisciplinary studies.
The search was conducted in February 2026, ensuring that the dataset captured the vast majority of publications from the full year of 2025. All retrieved publications were Chinese academic publications, including journal articles and dissertation papers, published between 2010 and 2025 that focused on hospital audit or related topics. Non-Chinese publications, conference abstracts, news items, and irrelevant studies were excluded. The initial dataset from CNKI was deduplicated using built-in tools and manually verified, followed by further screening based on relevance, document type, and completeness of metadata. During manual screening, studies were considered relevant if their primary focus was hospital audit or closely related topics, including internal audit, financial audit, operational audit, risk management, audit quality control, and audit-related management practices in hospital settings. Studies unrelated to hospital audit, such as general medical research, non-hospital organizational audits, or studies lacking sufficient bibliographic information, were excluded. Before bibliometric analysis, the retrieved records were further checked for the completeness and consistency of the bibliographic information. No additional keyword standardization or manual modification of keyword terms was performed. The original keyword data retrieved from the CNKI database were used for all subsequent analyses. Data related to author names, affiliations, publication type, keywords, and publication year were extracted.
Data analysis
Data visualization and statistical analyses were performed using the software and tools listed in the Table of Materials. Specifically, annual publication trends were plotted, and summary tables were generated. Co-authorship maps, keyword co-occurrence networks, and citation burst analyses were generated using the default software parameters to identify research hotspots and emerging topics in hospital audit research.
Results
Publications Statistics
A total of 6,534 records were initially retrieved from CNKI. After removing 72 duplicate records, 6,462 publications remained for screening. Following title, abstract, and keyword screening, 182 irrelevant records were excluded. Finally, 6,280 publications were included in the bibliometric analysis, providing the dataset for all subsequent analyses. Publications were classified into two document types. Research articles were the most common document type, accounting for 99.90% (n = 6,274) of the total publications, followed by dissertation papers (0.10%, n = 6). All publications were written in Chinese, as the CNKI database primarily consists of Chinese-language publications.
Number of publications
The annual number of publications related to hospital audit research in China from January 1, 2010, to December 31, 2025 is shown in Figure 1. The number of publications fluctuated over the study period, increasing from 160 in 2010 to 510 in 2025. Following a peak of 503 publications in 2019, the annual publication output declined to 289 in 2022 before increasing to 510 in 2025. Overall, the number of publications on hospital audit research in China increased over the study period.
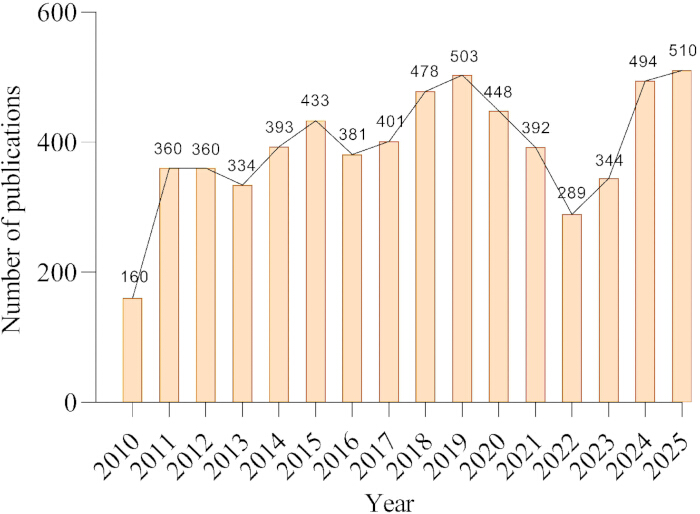
Figure 1. Annual number of publications on hospital audit research in China from 2010 to 2025.
Bar and line chart showing the annual number of publications on hospital audit research in China from 2010 to 2025. The x-axis represents the publication year, and the y-axis represents the number of publications. Values above the bars indicate the annual publication count. Please click here to view a larger version of this figure.
Authors analysis
Authors with a minimum of seven publications were selected for the co-authorship network analysis. Of the 6,011 authors identified, 33 met the inclusion threshold. The co-authorship network is shown in Figure 2. A total of 24 co-authorship clusters were identified. Ciyao Zhao had the highest number of publications. Hui Ang was linked to Ciyao Zhao, indicating collaboration between the two authors. The author network had a density of 0.045 and an average of 1.45 collaborators per author. In addition, 39% of authors were isolated nodes, indicating limited collaboration among research teams in this field.
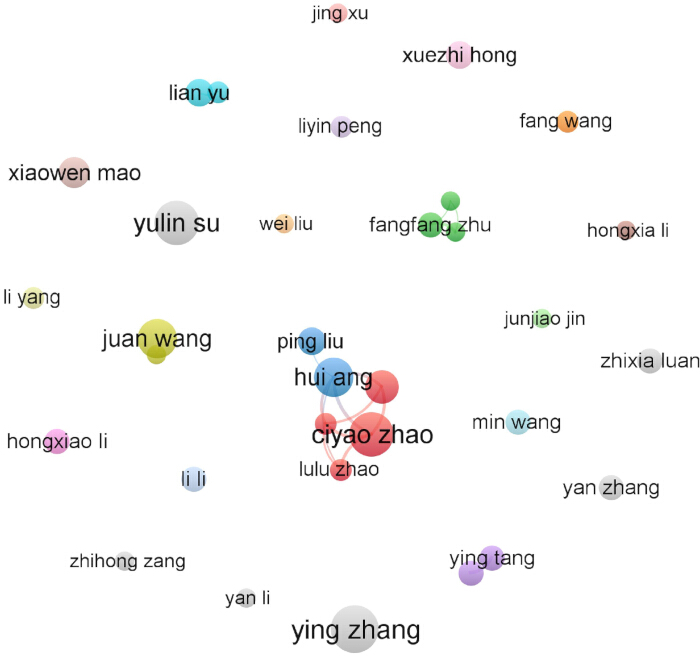
Figure 2. Co-authorship network of authors with seven or more publications.
Co-authorship network of authors with seven or more publications in hospital audit research. Each node represents an author, with node size proportional to the number of publications. Lines connecting nodes indicate co-authorship relationships, and shorter distances between nodes reflect stronger relatedness among authors. Different node colors represent distinct collaboration clusters. Please click here to view a larger version of this figure.
Keyword Analysis
The top 25 most frequently occurring keywords in hospital audit research are shown in Table 1. The most frequent keyword was “Hospital,” with 1,690 publications (26.91%), followed by “Public Hospital” (21.64%) and “Internal Audit” (19.73%). Other prominent keywords included “Internal Control” (16.86%), “Financial Management” (6.69%), and “Issues” (6.00%). Keywords such as “Countermeasures” (5.96%) and “Audit” (4.32%) also appeared frequently. In addition, the keyword “Management” accounted for 2.28% of the publications, whereas “China's new round of health system reform” appeared in 2.02% of the publications.
| Rank | Keyword | Publications, n | Percentage (%) |
| 1 | Hospital | 1690 | 26.91 |
| 2 | Public hospital | 1359 | 21.64 |
| 3 | Internal audit | 1239 | 19.73 |
| 4 | Internal control | 1059 | 16.86 |
| 5 | Financial management | 420 | 6.69 |
| 6 | Issues | 377 | 6 |
| 7 | Countermeasures | 374 | 5.96 |
| 8 | Audit | 271 | 4.32 |
| 9 | Management | 143 | 2.28 |
| 10 | China's new round of health system reform | 127 | 2.02 |
| 11 | Hospital management | 125 | 1.99 |
| 12 | Measures | 125 | 1.99 |
| 13 | Hospital finance | 110 | 1.75 |
| 14 | Hospital internal audit | 103 | 1.64 |
| 15 | Digitalization | 93 | 1.48 |
| 16 | Risk management | 91 | 1.45 |
| 17 | Finance | 84 | 1.34 |
| 18 | Financial risk | 83 | 1.32 |
| 19 | Hospital financial management | 73 | 1.16 |
| 20 | Risk | 67 | 1.07 |
| 21 | Current status | 66 | 1.05 |
| 22 | Internal financial control | 64 | 1.02 |
| 23 | Strategy | 61 | 0.97 |
| 24 | Recommendations | 60 | 0.96 |
| 25 | Financial accounting | 60 | 0.96 |
Table 1: Top 25 most frequently occurring keywords in hospital audit research.
The table lists the 25 most frequently occurring keywords identified in the retrieved publications, ranked by publication frequency. The Publications, n column indicates the number of publications in which each keyword appeared, and the Percentage (%) column indicates the proportion of retrieved publications containing each keyword.
Research hotspots and future trends
The keyword clustering network is shown in Figure 3. Fifteen keyword clusters were identified, representing the major research hotspots in hospital audit research. The clusters covered a broad range of topics, including key themes such as “Audit” (Cluster #1), “Internal Audit” (Cluster #5), and “Public Hospitals” (Cluster #2), which were closely related to the core concepts of hospital auditing. Other major clusters included “Hospital Finances” (Cluster #6), “Financial Management” (Cluster #10), and “Internal Controls” (Cluster #7), reflecting the financial and operational aspects of hospital auditing. Additional clusters included “Cybersecurity” (Cluster #3), “Risk Management” (Cluster #12), “Hospital Management” (Cluster #11), “Issues” (Cluster #4), and “Recommendations” (Cluster #13). To evaluate the reliability of the clustering structure, two quantitative metrics were examined: Modularity Q and Mean Silhouette S. The Modularity Q value was 0.7856, indicating a significant community structure within the network. The Mean Silhouette S value was 0.9124, suggesting high cluster homogeneity and supporting the reliability of the clustering results.
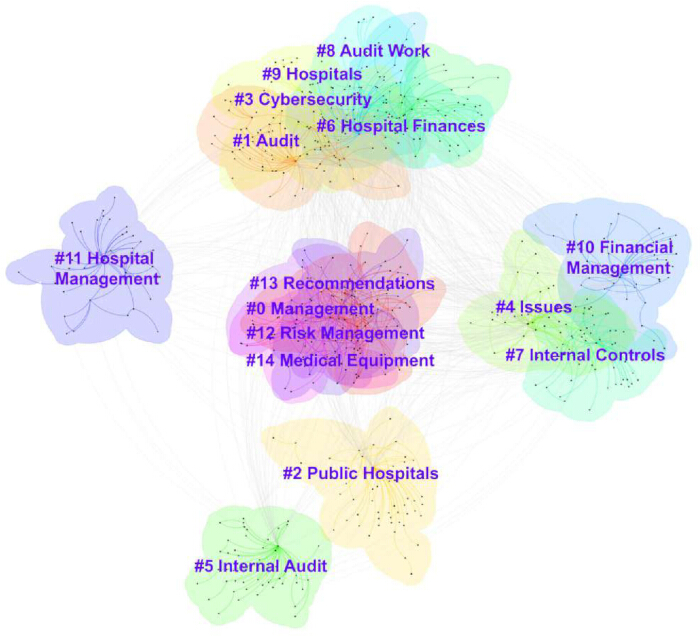
Figure 3. Keyword co-occurrence clusters in hospital audit research.
Keyword co-occurrence network showing thematic clusters in hospital audit research. Each node represents a keyword, with node size proportional to its occurrence frequency. Lines connecting nodes indicate keyword co-occurrence relationships, and shorter distances between nodes reflect stronger relatedness. Different colors represent distinct keyword clusters, and representative cluster labels are shown within each cluster. Please click here to view a larger version of this figure.
The top 25 keywords with the strongest citation bursts are shown in Figure 4. Hospital audit research over the study period can be broadly divided into three stages. During the first stage (2010–2015), the main burst keywords included “Management,” “Cost Accounting,” and “Hospital Accounting,” reflecting an early emphasis on administrative and financial management in hospital audits. During the second stage (2016–2020), keywords related to operational and systemic changes emerged, including “Operational Management,” “Cybersecurity,” and “New Medical Reform.” During the third stage (2021–2025), burst keywords included “Risk Prevention and Control,” “Contract Management,” and “Audit Rectification,” with increasing attention to digital transformation, big data, and cybersecurity.
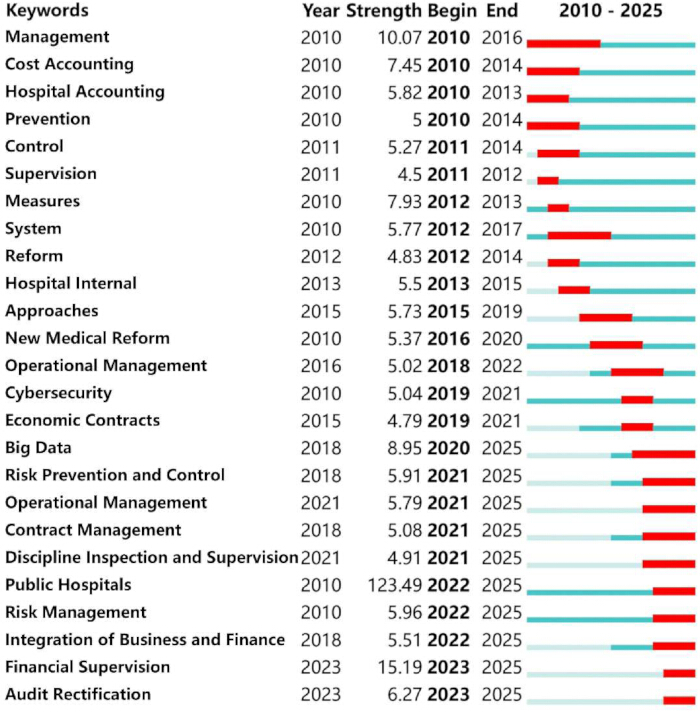
Figure 4. Top 25 keywords with the strongest citation bursts from 2010 to 2025.
Timeline showing the 25 keywords with the strongest citation bursts identified during the study period from 2010 to 2025. The columns indicate the keyword, year of first appearance (Year), burst strength (Strength), and the beginning (Begin) and ending (End) years of each citation burst. The light blue bars represent the full study period, and the red bars indicate the periods during which citation bursts occurred. Please click here to view a larger version of this figure.
Data Availability:
The raw data and supplementary materials used in this study are publicly available through the Zenodo repository at: https://sandbox.zenodo.org/records/512198.
Discussion
In recent years, research on hospital audits in China has increased substantially. However, the trends, research hotspots, and emerging frontiers in this field have not been comprehensively reported. This study focused on the period from January 2010 to December 2025 to explore the publication characteristics of hospital audit-related research. The findings indicated that, over the past 15 years, hospital audit research in China has concentrated on key themes, including internal audit, financial management, cybersecurity, medical equipment, risk management, and recommendations. Furthermore, the findings suggest that hospital audit research in China has increasingly focused on big data, risk prevention and control, operational management, contract management, financial and accounting supervision, and audit rectification. The number of publications on hospital auditing showed an overall upward trend from 2010 to 2025. However, after 2019, a decline in publication output was observed between 2019 and 2022. This downturn coincided with the period of the COVID-19 pandemic in China. The pandemic began in China at the end of 2019, and the control measures were not fully lifted until the end of 20229. Since the present bibliometric analysis did not examine factors influencing publication productivity, the reasons underlying this decline require further investigation.
Internal audit emerged as one of the most prominent research themes identified through the keyword co-occurrence analysis, indicating sustained scholarly attention to this topic in hospital audit research. Previous studies have mainly discussed hospital internal audit in the contexts of financial compliance auditing and operational auditing. Studies have shown that internal auditors in hospitals allocate the majority of their time to these two areas, which is similar to the internal audit functions in other industries10. The internal audit function has been reported to influence an institution's sustainable development and financial performance11. With the advancement of medical informatization and networking, cybersecurity issues have become increasingly prominent12. Hospitals with lower cybersecurity ratings have a significantly higher probability of data breaches, with annual breach probabilities ranging from 14% to 33%. Previous studies have reported that external ratings can effectively predict the risk of actual security incidents13. These findings highlight the growing attention to cybersecurity risks and information protection within healthcare institutions13. Moreover, medical equipment management and risk control were identified as important topics in hospital audit research. The frequent occurrence of these topics suggests sustained academic interest in hospital asset management and operational oversight. Previous studies have suggested categorizing equipment into major and minor categories based on value, allowing prioritized planning and ranking of major equipment, which reportedly accounts for 80% of the total asset value14. This approach provides a basis for equipment updates and procurement over the subsequent five years14. Such a classification strategy may help optimize resource allocation while providing data to support capital investment decisions.
Taken together, the identified research themes reflect different but related dimensions of hospital auditing. Internal audit and financial management are primarily concerned with organizational governance and resource accountability, whereas cybersecurity and medical equipment management focus on the auditing of information systems and physical assets. Risk prevention and control serves as a cross-cutting topic linked to multiple audit domains. The co-occurrence of these themes suggests that hospital audit research has gradually expanded from traditional financial supervision toward broader operational and risk-oriented management issues. These findings may provide a useful reference for hospital managers and policymakers when considering priorities for audit practice and governance improvement.
Keyword evolution analysis indicated increasing attention to big data-related topics, suggesting growing scholarly interest in the integration of digital technologies into hospital auditing research15. This observed increase in attention may reflect recent healthcare reforms and digital governance initiatives in China. In recent years, the National Health Commission and other governmental agencies have promoted the digital transformation of healthcare institutions through policies emphasizing hospital informatization, data governance, and intelligent management. Furthermore, the policy framework for the high-quality development of public hospitals has highlighted the importance of strengthening internal control systems, improving operational efficiency, and enhancing risk monitoring capabilities. Against this background, big data technologies have increasingly been applied to hospital auditing to support real-time monitoring, anomaly detection, and evidence-based decision-making. The growing research interest in big data therefore reflects not only technological advances but also the practical demands associated with healthcare governance reforms. In addition, recent burst keyword analysis identified risk prevention and control and contract management as emerging themes, indicating that these topics are attracting increasing research attention16,17. Financial and accounting supervision also emerged as a recent research focus, reflecting increasing scholarly interest in financial governance issues in hospitals18. Furthermore, audit rectification emerged as an important research topic, reflecting growing interest in how audit findings are addressed within hospital governance processes19,20. Collectively, these findings suggest that hospital audit processes in the context of digitalization and informatization are receiving increasing scholarly attention, as reflected by recent keyword trends and emerging research themes.
This study has several limitations. First, the analysis was based solely on the CNKI database, which represents a major academic source for hospital audit publications in China. As a result, relevant studies not included in the CNKI repository were not captured. Moreover, CNKI does not provide complete citation, institutional affiliation, or journal impact data for all publications. Consequently, additional bibliometric indicators, including citation analyses and analyses of influential authors, institutions, and journals, could not be comprehensively evaluated. Nevertheless, the present study provides a representative overview of research trends in hospital audit research in China. Second, the search strategy was based on predefined subject terms, which may have excluded relevant studies using different terminology. Finally, because of inconsistencies in the citation metadata provided by CNKI, regional collaboration network analyses were not performed. These findings may provide a useful reference for hospital audit managers and researchers by highlighting emerging research trends and identifying potential areas for future collaboration.
In conclusion, the bibliometric findings indicate that the focus of hospital audit research in China has evolved from an initial emphasis on finance and supervision to institutional reform and, more recently, to big data and risk prevention. These changes are reflected in the evolution of research themes and keyword patterns identified through the bibliometric analyses.
Disclosures
Conflict of Interest:
The authors declare no competing financial interests.
Materials
| Name | Company | Catalog Number | Comments |
|---|---|---|---|
| China National Knowledge Infrastructure (CNKI) database | China National Knowledge Infrastructure (CNKI), Beijing, China | N/A | Literature database used for bibliographic data retrieval. |
| CiteSpace software (Version 6.2R6) | Chaomei Chen, Drexel University, Philadelphia, PA, USA | N/A | Bibliometric analysis and visualization software. |
| VOSviewer software (Version 1.6.17) | Centre for Science and Technology Studies (CWTS), Leiden University, Leiden, The Netherlands | N/A | Bibliometric analysis and visualization software. |
References
- Abu-Jeyyab M, et al. The role of clinical audits in advancing quality and safety in healthcare services: a multiproject analysis from a Jordanian hospital. Cureus. 2024;16:e54764.
- Hanskamp-Sebregts M, Robben PB, Wollersheim H, Zegers M. Transparency about internal audit results to reduce the supervisory burden: a qualitative study on the preconditions of sharing audit results. Health Policy. 2020;124:216-223.
- Perlin JB, Mower L, Bushe C. A systems approach to evaluating ionizing radiation: six focus areas to improve quality, efficiency, and patient safety. J Healthc Qual. 2015;37:173-188.
- Sharma DVG, Gonzalez D. Clinical audit of the consultation-liaison psychiatric service of a metropolitan hospital. Australas Psychiatry. 2023;31:209-212.
- Zhu Y, et al. The hospital management practices in Chinese county hospitals and its association with quality of care, efficiency and finance. BMC Health Serv Res. 2021;21:449.
- Shi J, et al. Moving towards a better path? A mixed-method examination of China's reforms to remedy medical corruption from pharmaceutical firms. BMJ Open. 2018;8:e018513.
- Hassan W, Duarte AE. Bibliometric analysis: a few suggestions. Curr Probl Cardiol. 2024;49:102640.
- Li D, et al. Biochar-related studies from 1999 to 2018: a bibliometrics-based review. Environ Sci Pollut Res Int. 2020;27:2898-2908.
- Zheng L, Liu S, Lu F. Impact of the national Omicron outbreak at the end of 2022 on the future outlook of COVID-19 in China. Emerg Microbes Infect. 2023;12:2191738.
- Edwards D, Kusel J, Oxner T. Internal auditing in hospitals. Hosp Top. 2003;81:13-18.
- Khan U, Liu W. The role of internal auditing on corporate governance: its effects on economic and environmental performance. Environ Sci Pollut Res Int. 2023;30:112877-112891.
- Argaw ST, Bempong NE, Eshaya-Chauvin B, Flahault A. The state of research on cyberattacks against hospitals and available best practice recommendations: a scoping review. BMC Med Inform Decis Mak. 2019;19:10.
- Choi SJ, Johnson ME. The relationship between cybersecurity ratings and the risk of hospital data breaches. J Am Med Inform Assoc. 2021;28:2085-2092.
- Brown I, Smale A. Management of medical technology: case study of a major acute hospital. Annu Int Conf IEEE Eng Med Biol Soc. 2007;2007:1778-1781.
- Mehta N, Pandit A. Concurrence of big data analytics and healthcare: a systematic review. Int J Med Inform. 2018;114:57-65.
- Njoroge SW, Nichols JH. Risk management in the clinical laboratory. Ann Lab Med. 2014;34:274-278.
- Alexander J, Lewis BL. The financial characteristics of hospitals under for-profit and nonprofit contract management. Inquiry. 1984;21:230-242.
- Wu JS. Applying frontier approach to measure the financial efficiency of hospitals. Digit Health. 2023;9:20552076231162987.
- Hut-Mossel L, Welker G, Ahaus K, Gans R. Understanding how and why audits work: protocol for a realist review of audit programmes to improve hospital care. BMJ Open. 2017;7:e015121.
- Ogola M, et al. Audit identified modifiable factors in hospital care of newborns in low-middle income countries: a scoping review. BMC Pediatr. 2022;22:99.